

Most people only look at their money when something goes wrong. An overdraft alert. A declined card. A credit card bill that makes your stomach drop. But the smartest money habit you can build takes just ten minutes a month and prevents all of that.
A monthly money reset is a simple finance checkup routine: ten minutes, once a month, to review your balances, check your spending, update your savings goals, and set one clear money goal for the month ahead. That is it. No spreadsheets that take an hour. No financial anxiety spirals. Just a calm, quick check-in that keeps you in control.
Key Takeaways
- A monthly money reset is a 10-minute finance checkup routine that keeps your budget, spending, and savings on track without stress.
- Do your reset on the same day each month (the 1st works best) so it becomes an automatic habit.
- The five steps: check balances, review spending vs your budget, audit bills and subscriptions, update savings goals, and set one money goal for the month.
- Ten minutes a month is enough to catch leaks like forgotten subscriptions, budget creep, and missed savings transfers before they cost you hundreds.
- A monthly budget review works best with a simple budget framework like the 50/30/20 rule.
What Is a Monthly Money Reset?
A monthly money reset is a short, repeatable finance checkup you do once a month to review where your money went, how your savings are growing, and what one thing you want to improve next month. It usually takes about ten minutes and follows the same five steps every time: check your balances, compare spending to your budget, scan bills and subscriptions, update your savings goals, and set one new monthly money goal.
Think of it like a quick health checkup for your wallet. You are not doing a deep financial audit or rebuilding your whole budget. You are simply asking: “Am I on track? Anything leaking? What is my focus this month?” That small pause each month is what separates people who slowly build wealth from people who wonder where their paycheck went.
Why Does a Monthly Money Reset Matter?
A monthly money reset matters because small money problems become big ones when nobody is watching. The average household wastes over $130 a year on unused subscriptions alone, and studies show most people underestimate their monthly spending by 20 percent or more. Ten minutes of review each month catches these leaks early, before they quietly drain hundreds from your budget every year.
Without a regular checkup, your budget slowly drifts. You sign up for a free trial and forget to cancel. Grocery spending creeps up $50 at a time. Your savings transfer keeps “waiting until next month.” A monthly finance checkup resets the drift with one clean look at the real numbers each month, and those small monthly corrections compound into real money over a year.
When Should You Do Your Money Reset?
The best day for your monthly money reset is the 1st of the month, or the day right after your biggest paycheck arrives. Pick one fixed day and put a recurring reminder on your phone or calendar. When the reset has a fixed date, it becomes automatic instead of something you keep meaning to do. The 1st works well because it lines up with rent, bills, and fresh budget cycles, so everything you review is current.
Consistency beats perfection: if you miss a month, do the ten-minute version anyway, even if it is the 15th. Tie the reset to something you already do, like your first coffee of the month.
The 10-Minute Monthly Money Reset: Step by Step
Here is the exact routine. Set a timer for ten minutes and work through these five steps. Do them in order and do not skip ahead, because each step builds on the last.
Step 1: Check Your Balances (2 minutes)
Open your banking app and write down three numbers: your checking account balance, your savings account balance, and your total credit card debt. These three numbers are your financial snapshot. Compare them to last month. Is savings higher? Is credit card debt lower? That trend matters more than any single number, because a growing savings balance and shrinking debt mean your money reset is working.
Step 2: Review Your Spending vs Your Budget (3 minutes)
Pull up last month’s spending, either in your banking app’s spending summary or your budgeting app, and compare it to your plan. Most people need a simple framework here. The 50/30/20 budget rule is a great starting point: about 50 percent of take-home pay for needs, 30 percent for wants, and 20 percent for savings and debt payoff.
Do not audit every purchase. Look at the big categories: housing, groceries, dining out, shopping, and subscriptions. One category is usually the culprit when spending runs hot. If dining out was double your plan, you found your leak. This step is also where you catch the classic budgeting mistakes beginners make, like forgetting irregular expenses or setting an unrealistic grocery budget and blowing it by week two.
Step 3: Audit Your Bills and Subscriptions (2 minutes)
Scan your last 30 days of transactions for recurring charges. Streaming services, apps, memberships, cloud storage, subscription boxes. Ask one question about each: “Did I use this in the last month?” If the answer is no, cancel it on the spot. The average person pays for at least one subscription they forgot about, and these charges are silent budget killers.
While you are here, glance at your utility and phone bills. If anything jumped unusually, make a note to call and negotiate. Negotiating bills takes about fifteen minutes and can save you hundreds a year, so this two-minute scan often pays for itself many times over.
Step 4: Update Your Savings Goals (2 minutes)
Check each savings goal: emergency fund, vacation, car repair fund, whatever you are building. How much did you add this month? How close are you to the target? Update the numbers, even if progress was small. Seeing the balance move keeps you motivated, and a stagnant goal tells you the automatic transfer needs adjusting.
If your emergency fund is not growing, consider moving it to a high-yield savings account where it can earn 4 to 5 percent instead of sitting in a checking account earning almost nothing. Small rate differences matter over time, and your monthly reset is the perfect moment to make the move.
Step 5: Set One Money Goal for the Month (1 minute)
Pick exactly one money goal for the coming month. Not five. One. Examples: cancel two unused subscriptions, cook dinner at home four extra nights, move $100 into savings on payday, or pay $150 extra toward your highest-interest credit card. Write it down where you will see it, on a sticky note, your phone lock screen, or your fridge.
One goal works because it is specific and doable. Twelve goals mean none of them happen. Next month, your reset starts by checking whether you hit this one, which keeps the whole system honest.
What Should You Do If Your Budget Is Off Track?
If your monthly budget review shows you overspent, do not panic and do not abandon the budget. Overspending is information, not failure. First, identify the one category that caused the biggest gap and shrink it next month by a realistic amount, like cutting dining out from $400 to $300 instead of to zero. Second, check whether the budget itself is the problem: an unrealistic plan fails every time, so adjust the numbers to match your real life.
Third, look for one quick win this month, like canceling a subscription or doing a no-spend week on non-essentials, to recover some of the gap. And if overspending is a pattern, read up on the common money mistakes keeping you poor so you can fix the root cause instead of the symptom. The reset is working exactly as designed when it helps you catch the problem in month one instead of month six.
A Simple Money Reset Checklist You Can Reuse
Save this checklist in your phone’s notes app and run through it on your reset day. It covers everything that matters.
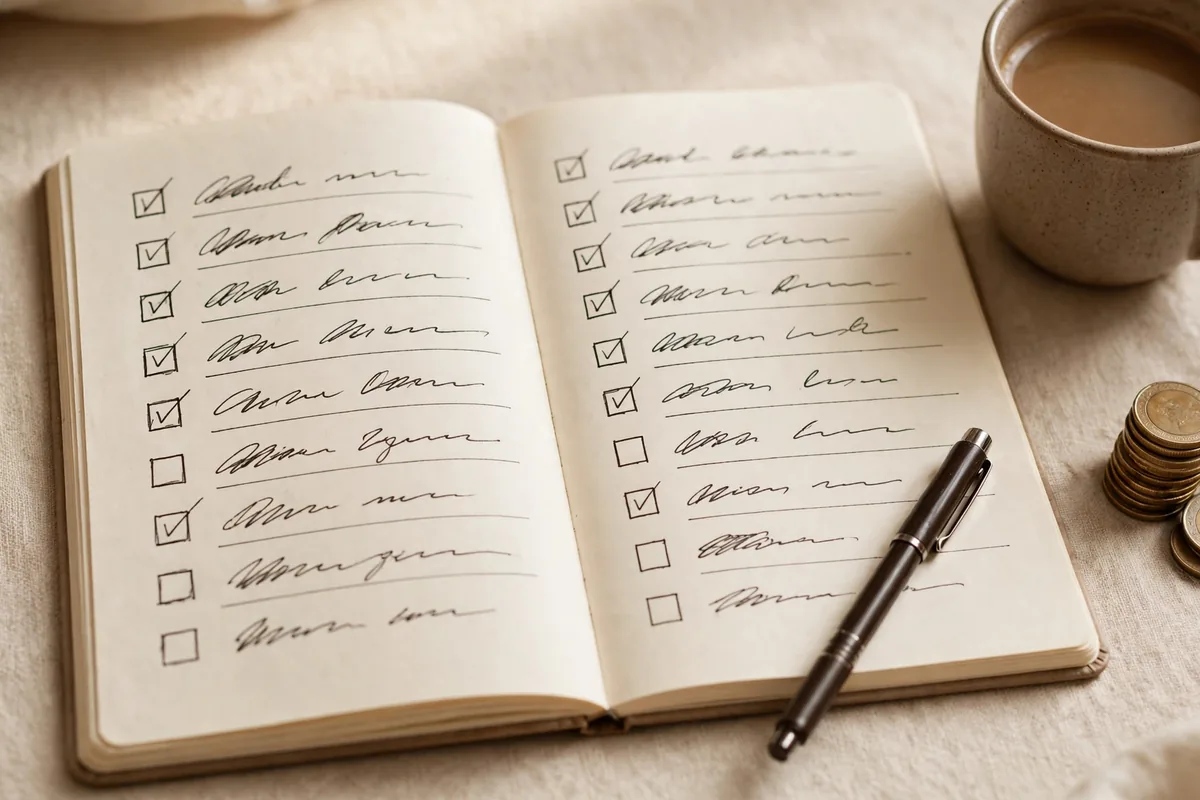
- Write down checking balance, savings balance, and credit card debt
- Compare spending to your budget in the big categories (housing, groceries, dining, shopping, subscriptions)
- Cancel or pause any subscription you did not use last month
- Update every savings goal with this month’s progress
- Confirm your automatic savings transfer is still active
- Check for any unusual or unexpected charges
- Set one specific money goal for the coming month
- Note your one biggest win from last month to stay motivated
Frequently Asked Questions
How long does a monthly money reset really take?
A monthly money reset takes about ten minutes once you know the routine. The first time might take twenty minutes because you are setting everything up and finding your numbers. By the third month, most people finish in under ten minutes because the steps are familiar and the numbers are already organized.
What if I do not have a budget yet?
You can still do a monthly money reset without a formal budget. Just track the three numbers from Step 1 and scan your spending by category in Step 2. The reset will show you your natural spending pattern, and after two or three months you will have enough data to build a realistic budget around it.
Should I do a money reset weekly or monthly?
Monthly is the sweet spot for most people. Weekly reviews take more effort and can feel like micromanaging, which is why people quit. A monthly finance checkup catches problems fast enough to fix them while staying light enough to actually stick with. If you are actively paying off debt, add a quick weekly glance at balances, but keep the full reset monthly.
What is the difference between a money reset and a budget?
A budget is your plan for how money should flow each month. A money reset is the ten-minute monthly checkup that tells you whether you followed the plan and what to adjust. The budget is the map; the reset is checking your location. You need both, because even a great budget drifts without regular review.
Can a 10-minute checkup really improve my finances?
Yes, because it fixes the biggest problem in personal finance: not paying attention. Ten focused minutes a month prevents the silent leaks, forgotten subscriptions, and drifting budgets that cost the average person hundreds a year. Looking regularly is what makes every other money habit work.
Start Your First Money Reset Today
You do not need a perfect budget or a fancy app. You need ten minutes, your banking app, and the five steps above. Do your first monthly money reset today, then schedule the next one for the 1st of next month.
Ten minutes a month is a tiny price for always knowing exactly where your money stands. Run the checklist, set your one goal for this month, and enjoy the calm that comes from being in control. Your future self, with the growing savings balance and shrinking debt, will thank you for starting now.