

Introduction
How to invest for retirement in your 20s comes down to 4 moves: capture the full employer 401(k) match, open a Roth IRA, invest 90 to 100 percent in low-cost stock index funds, and automate every contribution on payday. A 25-year-old who invests $200 a month at a 7 percent average annual return holds about $525,000 at 65.
This Savvy Cash Flow guide turns small paychecks into a large retirement balance through time, tax breaks, and low fees. This guide defines the habit, shows the math behind starting at 25 instead of 35, sets the 15 percent savings target, ranks the accounts in order, lists the 2026 contribution limits, gives 7 steps to start, covers freelance workers, shows a worked example on a $35,000 salary, explains the job-change rollover, lists 5 mistakes to avoid, and ends with a 12-month plan and 6 FAQs.
Key Takeaways
- How to invest for retirement in your 20s starts with the employer 401(k) match, then a Roth IRA, then more 401(k) contributions.
- A 25-year-old who invests $200 a month at a 7 percent average annual return holds about $525,000 at 65, while the same habit started at 35 holds about $244,000.
- Aim to save 15 percent of pre-tax income for retirement each year, including the employer match, and hold 1x salary by age 30 (Source: Fidelity, 2026).
- The 2026 limits are $24,500 for a 401(k) and $7,500 for an IRA, and a Roth IRA phases out at $153,000 to $168,000 for single filers (Source: IRS, 2026).
- Freelancers can use a Solo 401(k), a SEP IRA, or a SIMPLE IRA, and a worker on a $35,000 salary can still reach a 12 percent savings rate.
What Is Investing for Retirement in Your 20s?
Investing for retirement in your 20s is a savings habit that puts a set share of each paycheck into tax-advantaged accounts that grow for 40 years before withdrawal. Investing for retirement in your 20s is not stock picking, and it is not a get-rich plan. Investing for retirement in your 20s is a system with 4 parts: a 401(k) or similar workplace plan, a Roth IRA (Individual Retirement Account), low-cost index funds, and automatic monthly contributions.
A 401(k) is an employer plan that takes contributions from pay before tax, and many employers add matching money. A Roth IRA (Individual Retirement Account) is an account you open yourself with after-tax money, and qualified withdrawals in retirement are tax-free. An index fund is a fund that holds hundreds of stocks at once and charges a low fee. The Investing & Wealth guides on Savvy Cash Flow cover each account type in more depth, with plain-word explainers for beginners.
Why Does Starting at 25 Beat Starting at 35?
Starting at 25 beats starting at 35 because compound growth rewards time more than amount: $200 a month from age 25 grows to about $525,000 by 65, while the same $200 a month from age 35 grows to about $244,000. The 25-year-old contributes only $24,000 more and ends with $281,000 more. Time does the extra work.
Compound interest is interest earned on the original amount plus interest earned in earlier periods, so each year adds interest to a larger balance than the year before. The table below shows the same $200 monthly habit at a 7 percent average annual return, started at 3 ages. The figures are illustrations, not promises, because real returns vary each year.
| Start age | Monthly amount | Total contributed | Balance at 65 |
|---|---|---|---|
| 25 | $200 | $96,000 | $525,000 |
| 30 | $200 | $84,000 | $365,000 |
| 35 | $200 | $72,000 | $244,000 |
The gap grows with each year of delay. A dollar invested at 25 has 40 years to grow, and a dollar invested at 35 has 30 years. The 10-year head start more than doubles the ending balance on the same monthly amount. For the full math behind the growth curve, read the guide to how compound interest works with real examples.
How Much Should You Save for Retirement in Your 20s?
You should save 15 percent of your pre-tax income for retirement each year in your 20s, including any employer match, and hold 1x your salary by age 30. Fidelity sets the 15 percent guideline, and the same guideline sets the age benchmarks: 1x salary by 30, 3x salary by 40, 6x salary by 50, 8x salary by 60, and 10x salary by 67 (Source: Fidelity, 2026).
| Age | Savings target | Example at $50,000 salary | Example at $70,000 salary |
|---|---|---|---|
| 25 | 0.5x salary | $25,000 | $35,000 |
| 27 | 0.75x salary | $37,500 | $52,500 |
| 30 | 1x salary | $50,000 | $70,000 |
Fidelity built the 15 percent guideline on one finding: most people need 55 to 80 percent of pre-retirement income to keep the same lifestyle in retirement, and savings must supply about 45 percent of that income, with Social Security covering the rest (Source: Fidelity, 2026). A worker who earns $54,000 at 25 and gets a 5 percent employer match needs to save 10 percent of pay to reach the 15 percent total (Source: Fidelity, 2026).
The 15 percent target is a direction, not a pass-or-fail test. The average 401(k) contribution rate is 7.4 percent of salary (Source: Vanguard, 2024), and the median 401(k) balance for Americans in their 30s is about $21,000 (Source: Federal Reserve, 2022). A beginner who starts at 5 percent, captures the full match, and raises the rate 1 percent each year reaches 15 percent in a decade. For a monthly version of the same target, read how much to invest each month for a simple 2026 guide.
Which Retirement Accounts Should You Open First?
You should open retirement accounts in this order: a starter emergency fund, a 401(k) up to the full employer match, high-interest debt payoff, a Roth IRA, and then more 401(k) contributions or a Health Savings Account (HSA). The order follows the return on each dollar: the employer match is a 50 to 100 percent instant return, the Roth IRA gives decades of tax-free growth, and extra 401(k) money adds tax-deferred growth.
- Build a $1,000 starter emergency fund. A starter fund stops surprise costs from forcing a retirement withdrawal. Keep it in a high-yield savings account, then build it to 3 months of costs later.
- Contribute to the 401(k) up to the full match. A common match is 50 percent of the first 6 percent of pay, which turns a 6 percent contribution into 9 percent of pay. A dollar-for-dollar match up to 3 percent of pay is a 100 percent instant return.
- Pay off high-interest debt. Credit card debt at 18 to 25 percent costs more than investments earn, so pay it off before investing past the match. Student loans at lower rates can run beside retirement saving.
- Open a Roth IRA. A Roth IRA fits a worker in the 20s because tax rates in the 20s are often the lowest of a career. Pay tax now at a low rate, and take qualified withdrawals tax-free in retirement.
- Go back to the 401(k), then an HSA or a taxable brokerage account. After the Roth IRA is full, raise 401(k) contributions toward the annual limit. A Health Savings Account (HSA) gives a triple tax break for workers on a high-deductible health plan: tax-deductible contributions, tax-free growth, and tax-free withdrawals for medical costs.
| Feature | Traditional 401(k) | Roth IRA |
|---|---|---|
| Tax on contributions | Pre-tax, lowers taxable income now | After-tax, no deduction now |
| Tax on growth | Tax-deferred | Tax-free |
| Tax on retirement withdrawals | Taxed as ordinary income | Tax-free if qualified |
| 2026 limit | $24,500 | $7,500 |
| Income limits | None | Phases out at $153,000 to $168,000 single in 2026 |
| Required withdrawals | Yes, from age 73 | No, during the owner lifetime |
Check the vesting schedule before counting match money as yours. Vesting decides when employer match money becomes yours to keep. Cliff vesting gives nothing until a set date, often 2 or 3 years, then 100 percent. Graded vesting gives a growing share each year, such as 20 percent per year over 5 years. Your own contributions are always 100 percent yours at once.
What Are the 2026 Contribution Limits for Retirement Accounts?
The 2026 contribution limits are $24,500 for a 401(k), $7,500 for an IRA, and $17,000 for a SIMPLE IRA, and the Roth IRA income phase-out starts at $153,000 for single filers. The limits come from the IRS 2026 contribution limits announcement, and the figures below match that announcement (Source: IRS, 2026).
| Account | 2026 limit, under age 50 | 2026 limit, age 50 or older |
|---|---|---|
| 401(k), 403(b), or 457 plan | $24,500 | $32,500 |
| IRA (Traditional or Roth, combined) | $7,500 | $8,600 |
| SIMPLE IRA | $17,000 | $21,000 |
| Roth IRA income phase-out, single | $153,000 to $168,000 | Same range |
| Roth IRA income phase-out, married filing jointly | $242,000 to $252,000 | Same range |
The IRA limit is combined across every IRA you own: $4,000 in a Traditional IRA leaves only $3,500 of room in a Roth IRA in the same year. Total IRA contributions also cannot exceed taxable compensation for the year. A worker who earns $4,000 in a year can contribute at most $4,000 across all IRAs. The Saver’s Credit gives a tax credit to low- and moderate-income savers, with an income limit of $40,250 for single filers and $80,500 for married couples filing jointly in 2026 (Source: IRS, 2026).
How Do You Invest for Retirement in Your 20s in 7 Steps?
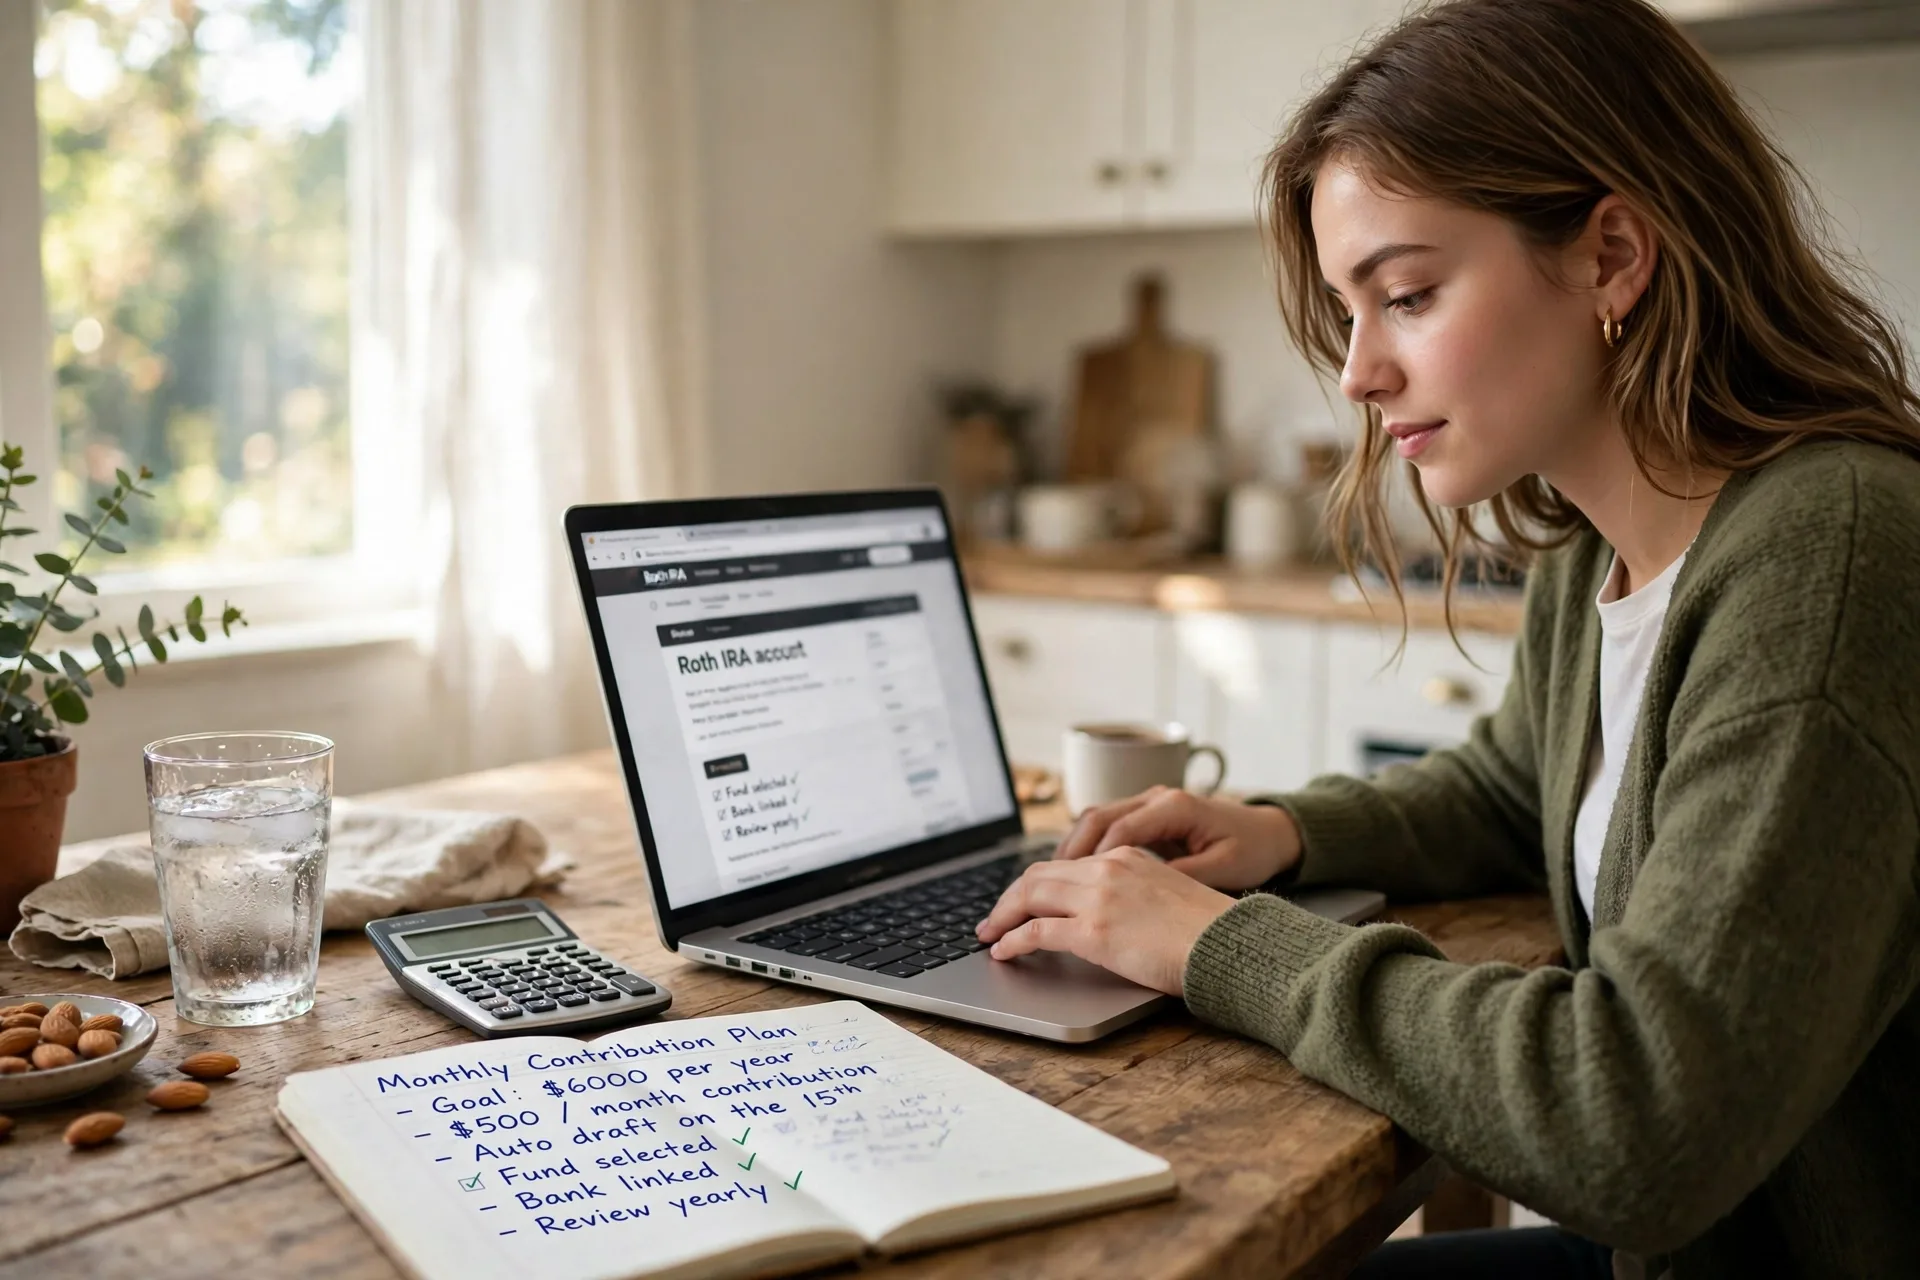
To invest for retirement in your 20s, follow 7 steps: build a $1,000 starter fund, capture the full 401(k) match, open a Roth IRA, pick one low-cost index fund, automate contributions on payday, raise the rate 1 percent a year, and review the plan each January. The 7 steps take one month to set up and about 30 minutes a year to keep.
- Build a $1,000 starter emergency fund. Open a high-yield savings account and move $50 to $100 per paycheck until the balance hits $1,000. A starter fund keeps a car repair or a medical bill from touching retirement money. For the full fund plan, read how to build an emergency fund from scratch.
- Enroll in the 401(k) and capture the full match. Ask HR for the match formula, then set the contribution rate to the level that gets every match dollar. A 6 percent contribution with a 50 percent match on the first 6 percent puts 9 percent of pay into retirement.
- Open a Roth IRA at a low-cost brokerage. Pick a provider with no account fee and low-cost index funds. Complete the application, link a bank account, and set an automatic monthly transfer.
- Buy one broad index fund or a target-date fund. A total stock market index fund holds hundreds of companies in one purchase. A target-date fund set to 2060 or 2065 picks the stock and bond mix and shifts it as retirement nears. Keep the expense ratio under 0.20 percent.
- Automate every contribution on payday. Set the 401(k) deduction through payroll and the Roth IRA transfer for payday. Money that moves before it hits checking never gets spent.
- Raise the rate 1 percent each year. Tie each raise to a pay raise or to January 1. A 1 percent yearly rise lifts a 6 percent rate to 16 percent in 10 years, and the paycheck barely feels each step.
- Review the plan each January. Check the total saved, the fund fees, and the new IRS limits. Confirm the Roth IRA total stayed under $7,500 and the 401(k) total stayed under $24,500.
When I opened my first Roth IRA, I set a $100 monthly transfer on payday and raised it to $150 after 3 months, because a small transfer that runs on its own beats a large plan that never starts.
Compare the two IRA types first: Roth IRA vs Traditional IRA explains the tax choice in plain words.
What If You Freelance or Have No 401(k)?
If you freelance or have no 401(k), open a Roth IRA first, then add a Solo 401(k), a SEP IRA (Simplified Employee Pension IRA), or a SIMPLE IRA (Savings Incentive Match Plan for Employees IRA) for larger contributions. Gig work, freelance work, and part-time jobs without a workplace plan still leave 3 strong retirement accounts open.
- Roth IRA: Open a Roth IRA first, because it needs only taxable compensation, not an employer. The 2026 limit is $7,500, and the same income phase-outs apply.
- Solo 401(k): A Solo 401(k) fits a freelancer with no employees. You contribute as both employee and employer, up to a combined $72,000 in 2026 (Source: IRS, 2026). A Solo 401(k) holds the most room of any account for a high-earning freelancer.
- SEP IRA (Simplified Employee Pension IRA): A SEP IRA lets a freelancer contribute up to 25 percent of net self-employment income. A SEP IRA takes one form to open and holds only employer contributions, so the freelancer funds it as the employer.
- SIMPLE IRA (Savings Incentive Match Plan for Employees IRA): A SIMPLE IRA fits a small business with under 100 employees. The 2026 limit is $17,000, and the employer adds a match or a fixed contribution (Source: IRS, 2026).
A freelancer should also set tax money aside before investing. Freelance income has no payroll tax withholding, so hold 20 to 25 percent of each payment in a separate savings account for tax. Invest from the money left after the tax hold, not before it.
How Do You Invest for Retirement on a $35,000 Salary?
You invest for retirement on a $35,000 salary by saving 6 percent in the 401(k) for the match, adding $100 a month to a Roth IRA, and keeping $50 a month for the emergency fund, which puts 12.4 percent of gross pay into retirement. The plan below uses a $35,000 salary, a 50 percent match on the first 6 percent of pay, and a $2,400 monthly take-home pay.
| Monthly move | Amount | Share of gross pay |
|---|---|---|
| 401(k) contribution, 6 percent | $175 | 6.0 percent |
| Employer match, 50 percent of 6 percent | $87.50 | 3.0 percent |
| Roth IRA contribution | $100 | 3.4 percent |
| Emergency fund transfer | $50 | 1.7 percent |
| Total into retirement accounts | $362.50 | 12.4 percent |
The 12.4 percent rate sits close to the 15 percent target, and it leaves about $2,075 a month for rent, food, transport, and debt payments. A $50 monthly Roth IRA contribution also works as a start: at a 7 percent average annual return, $50 a month from age 22 to 65 grows to about $164,000 as an illustration. The Saver’s Credit adds help at this income: single filers with income under $40,250 in 2026 may claim a tax credit for retirement contributions (Source: IRS, 2026).
Low pay is not a reason to wait. A worker who starts at $50 a month and raises the amount with each pay raise builds the habit first and the balance second. The raise path matters more than the start amount: a 1 percent yearly rise plus a $25 bump at each raise closes most of the gap to 15 percent in 5 years.
What Should You Do With Your 401(k) When You Change Jobs?
When you change jobs, roll your old 401(k) into your new employer plan or into an IRA, and do not cash it out. You have 4 options, and only one of them destroys the balance.
| Option | What happens | Best when |
|---|---|---|
| Leave it with the old employer | Money stays invested, no action needed | The old plan has low fees and good funds |
| Roll it into the new 401(k) | Money moves to the new plan, one account to watch | The new plan has low fees and good funds |
| Roll it into an IRA | Money moves to an IRA you control, with wide fund choice | You want the most fund choice and the lowest fees |
| Cash it out | You get the balance minus tax and a 10 percent penalty | Almost never, only in a true emergency |
Cashing out costs more than the tax bill shows. A $15,000 401(k) cashed out at 25 in the 22 percent tax bracket loses about $4,800 at once to tax and the 10 percent penalty, and loses about $200,000 in growth by age 65. Use a direct rollover: the old provider sends the money straight to the new account, so no tax is withheld and no 60-day clock starts. Check the vesting schedule first, because unvested match money stays with the old employer when you leave.
What Mistakes Should You Avoid in Your 20s?
You should avoid 5 mistakes in your 20s: skipping the employer match, waiting to start, picking single stocks as the core plan, cashing out a 401(k) on a job change, and leaving cash uninvested inside the account. Each mistake costs more at 25 than at 45, because lost years cannot be bought back.
- Skipping the employer match. A worker who skips a 3 percent match on a $50,000 salary leaves $1,500 a year on the table, plus decades of growth on that money.
- Waiting to start. Waiting from 25 to 35 on a $200 monthly habit cuts the age-65 balance from about $525,000 to about $244,000 at a 7 percent average annual return.
- Picking single stocks as the core plan. One stock can fall 50 percent and stay down for years. A broad index fund holds hundreds of stocks, so one bad company cannot sink the plan.
- Cashing out a 401(k) on a job change. A $15,000 cash-out at 25 loses about $4,800 at once and about $200,000 in growth by 65. A direct rollover keeps every dollar invested.
- Leaving cash uninvested inside the account. An open Roth IRA with no investments earns no market growth. Buy the index fund in the same sitting as the account opening, then set contributions on repeat.
Your First 12 Months: A Month-by-Month Plan
Your first 12 months of investing for retirement in your 20s run in 6 two-month blocks: set up the 401(k) and starter fund, open the Roth IRA, pick the fund, check fees and vesting, add the HSA, and review the year. The plan below needs about 2 hours of setup in month 1 and about 30 minutes a month after that.
| Months | Moves |
|---|---|
| 1 to 2 | Enroll in the 401(k) at the full match rate. Open a high-yield savings account and move $100 per paycheck to the starter fund. |
| 3 to 4 | Open a Roth IRA and set a $50 to $100 monthly transfer on payday. List high-interest debts and pay the smallest one first. |
| 5 to 6 | Buy one total stock market index fund or a 2060 target-date fund inside the Roth IRA. Set the 401(k) to auto-escalate 1 percent a year. |
| 7 to 8 | Read the 401(k) vesting schedule and fund fee list. Switch any fund with an expense ratio over 0.50 percent to a lower-cost fund. |
| 9 to 10 | Open a Health Savings Account (HSA) if the health plan qualifies. Raise the Roth IRA transfer by $25. |
| 11 to 12 | Review the year: total saved, fees paid, and new IRS limits. Set the next-year target: 1 percent more of pay, and 1x salary by 30. |
FAQs About Investing for Retirement in Your 20s
How much should I have saved for retirement by 30?
You should have 1x your annual salary saved for retirement by 30. A worker who earns $50,000 should hold $50,000 across retirement accounts by the 30th birthday, and a worker who earns $70,000 should hold $70,000 (Source: Fidelity, 2026). The target assumes saving 15 percent of income from age 25.
Is a Roth IRA or a 401(k) better in your 20s?
Neither account wins on its own: use both, with the 401(k) first up to the match and the Roth IRA second. The 401(k) match is a 50 to 100 percent instant return, and the Roth IRA adds decades of tax-free growth at a low early-career tax rate. Then raise 401(k) contributions toward the $24,500 limit.
Can I invest for retirement while paying student loans?
Yes, you can invest for retirement while paying student loans, and you should capture the employer match first. Pay minimums on loans and contribute enough to get the full match, then send extra cash to loans above 8 to 10 percent APR. Some employers now match student loan payments with 401(k) contributions, so ask HR if your plan offers it.
How much money do I need to start investing for retirement?
You can start investing for retirement with $50 a month. Many brokerages let you buy fractional shares with $1, so no large lump sum is needed. A $50 monthly habit from age 22 to 65 grows to about $164,000 at a 7 percent average annual return. The habit matters more than the start amount. Raise it 1 percent a year.
What happens to my 401(k) if I quit my job?
Your 401(k) stays yours when you quit, and you can leave it, roll it into the new plan, or roll it into an IRA. Your own contributions are always 100 percent yours, while unvested match money can stay behind. A direct rollover moves the money with no tax withheld, and cashing out costs income tax plus a 10 percent penalty.
Should I pay off debt or invest for retirement first?
Capture the employer match first, then pay off debt above 8 to 10 percent APR, then invest more for retirement. The match is a 50 to 100 percent instant return that no debt payoff can match. After the match, high-interest debt costs more than investments earn, so clear it next. Low-rate student loans can run beside retirement saving.
Conclusion
How to invest for retirement in your 20s is a short list done on repeat: capture the full 401(k) match, open a Roth IRA, buy one low-cost index fund, automate every contribution on payday, and raise the rate 1 percent each year. A 25-year-old who invests $200 a month at a 7 percent average annual return holds about $525,000 at 65, while the same habit started at 35 holds about $244,000, so the start date matters more than the start amount. Check the 2026 limits, pick the account order that fits your job, and run the 12-month plan in this guide. Savvy Cash Flow publishes beginner money guides each week, so the next step is one small transfer on the next payday.
This guide is for education only and is not personal financial advice. Contribution limits, tax rules, and income phase-outs change each year, so check the current IRS figures before you contribute.