

If you have ever tried to budget and felt overwhelmed by complicated spreadsheets, percentage-based budget methods are about to become your best friend. The 50/30/20 vs 70/20/10 budget debate is one of the most common questions beginners ask, because both rules promise the same thing: a simple way to split your paycheck without tracking every dollar.
Here is the short answer: both rules save you the same 20% of your income. The difference is how they treat the other 80%. The 50/30/20 budget splits spending into needs, wants, and savings, while the 70/20/10 budget rolls all spending into one big bucket and adds a dedicated slice for debt payoff or giving. Neither is universally better, but one of them almost certainly fits your life better than the other.
Key Takeaways
- The 50/30/20 budget rule sends 50% of income to needs, 30% to wants, and 20% to savings. The 70/20/10 budget sends 70% to all expenses, 20% to savings, and 10% to debt payoff or giving.
- Both rules target the same 20% savings rate, so the “winner” depends on your spending habits, not the math.
- 50/30/20 works best if you need a clear line between needs and wants, especially if lifestyle creep is your biggest problem.
- 70/20/10 works best if you live in a high-cost area, carry debt, or want to formalize charitable giving in your budget.
- You can start with one method and switch later, or blend them into a hybrid.
What Is the 50/30/20 Budget Rule?
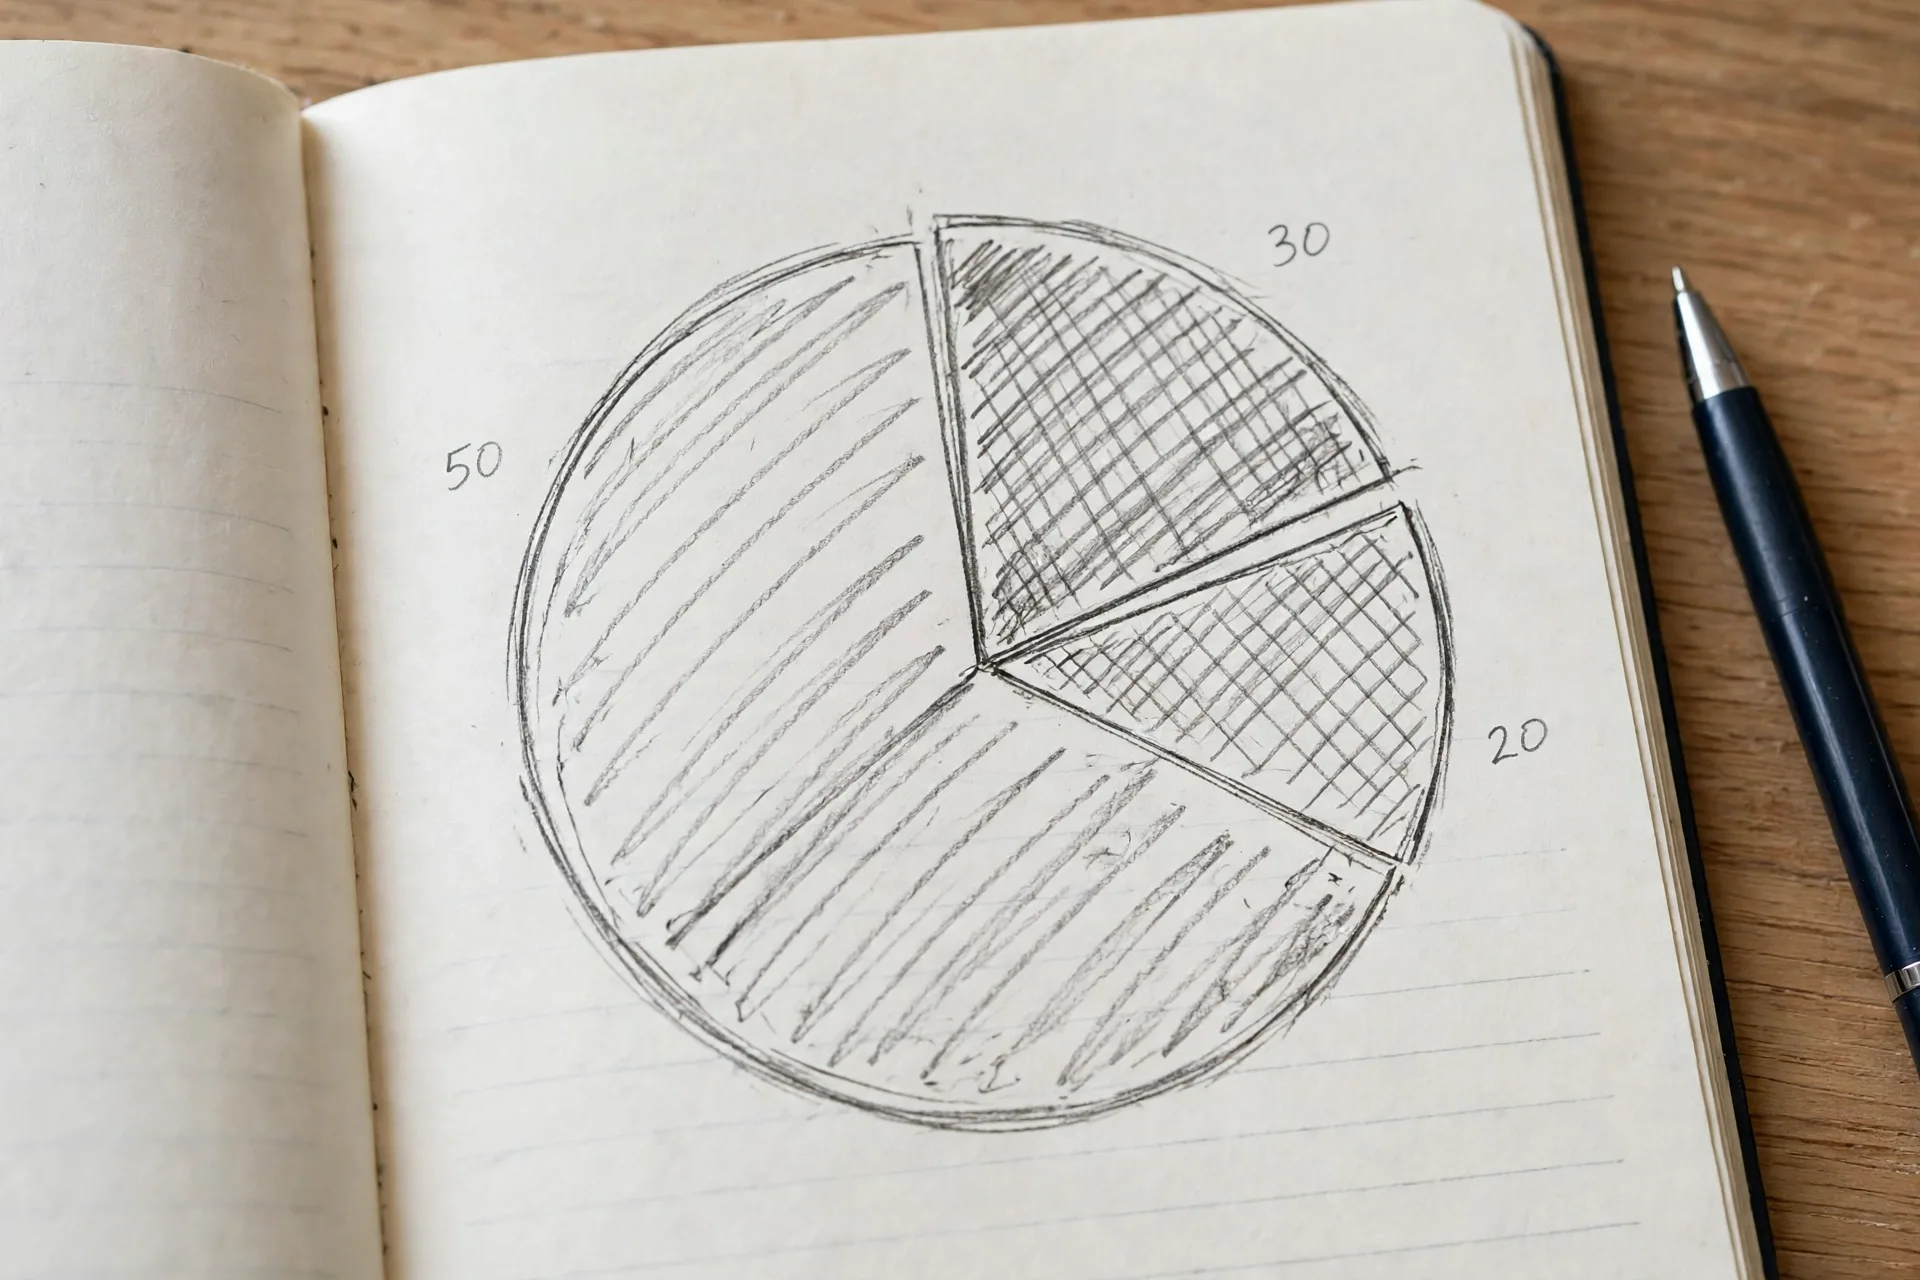
The 50/30/20 budget rule is a percentage-based method that divides your after-tax income into three buckets: 50% for needs (rent, groceries, insurance, minimum debt payments), 30% for wants (dining out, subscriptions, hobbies), and 20% for savings and extra debt payments. It was popularized by Senator Elizabeth Warren in her book “All Your Worth” as a simple, balanced approach to money management.
The strength of this method is the hard line it draws between needs and wants. When takeout and streaming share the same 30% bucket, it gets much harder to trick yourself into thinking a want is a need. Our full 50/30/20 budget rule guide walks through it step by step.
What Is the 70/20/10 Budget Rule?
The 70/20/10 budget rule is a percentage-based method that divides your after-tax income into three buckets: 70% for all living expenses (needs and wants combined), 20% for savings and investments, and 10% for debt payoff or charitable giving. You never have to decide whether an expense is a need or a want, which makes it simpler to track.
The standout feature of 70/20/10 is the dedicated 10% slice for extra payments on credit cards and loans, or for donations if you are debt-free.
50/30/20 vs 70/20/10 Budget: The Real-Number Breakdown
How do the 50/30/20 and 70/20/10 budget rules compare on a real paycheck? On a $4,000 monthly take-home income, 50/30/20 gives you $2,000 for needs, $1,200 for wants, and $800 for savings. 70/20/10 gives you $2,800 for all expenses, $800 for savings, and $400 for debt payoff or giving.
| Budget Bucket | 50/30/20 ($4,000 income) | 70/20/10 ($4,000 income) |
|---|---|---|
| Needs | $2,000 (50%) | Part of 70% bucket |
| Wants | $1,200 (30%) | Part of 70% bucket |
| All expenses combined | Not separated | $2,800 (70%) |
| Savings and investments | $800 (20%) | $800 (20%) |
| Extra debt payments or giving | Included in savings bucket | $400 (10%) |
Notice the savings are identical at $800 per month, which is $9,600 a year before interest. The difference is entirely in how the remaining $3,200 is organized. 50/30/20 gives you a built-in spending limit on fun money, while 70/20/10 gives you a built-in debt-payoff or giving lane.
Which Budget Method Helps You Save More Money?
Neither the 50/30/20 nor the 70/20/10 budget rule saves more money on paper, because both reserve the same 20% for savings. The method that saves you more is the one you will follow for longer than a few weeks. Consistency beats optimization every time.
That said, 70/20/10 can quietly outperform 50/30/20 for people carrying high-interest debt. The dedicated 10% slice on a $4,000 income means $400 every month toward debt on top of minimum payments, which clears a $6,000 balance at 22% APR in about 17 months and saves roughly $1,000 in interest.
Conversely, if your biggest problem is lifestyle creep rather than debt, 50/30/20 protects you better. The separate 30% wants bucket forces you to see exactly how much of your income goes to fun spending, which is the first step to controlling it. Either way, pairing your rule with proven ways to save money every month puts the extra room it creates to good use.
Which Budget Method Is Easier to Stick With?
The 70/20/10 budget is easier to track because it removes the most annoying part of budgeting: classifying every purchase as a need or a want. Under 50/30/20, you have to decide whether new sneakers are a need or a want, and that classification fatigue is one of the top reasons people abandon their budgets.
Under 70/20/10, you only need to track one number: total spending against the 70% cap. Simple rules are stickier rules, and the best budgeting method for beginners is always the one that survives contact with real life.
When Should You Choose the 50/30/20 Budget?
The 50/30/20 budget is the better choice when you need clearer spending discipline. If you regularly look at your bank statement and wonder where your money went, the separate needs and wants buckets show you exactly which lane you drifted out of.
Choose 50/30/20 if any of these sound like you:
- You are building a budget for the first time and want clear, memorable categories.
- Lifestyle creep is your main problem: income rises but savings never do.
- You like structure and find that simple frameworks keep you honest.
One important note: in expensive cities, the 50% needs cap can feel impossible. If rent alone eats 45% of your income, do not panic. You can temporarily adjust the split to something like 60/20/20 and work back toward 50/30/20 as your income grows.
When Should You Choose the 70/20/10 Budget?
The 70/20/10 budget is the better choice when your expenses are already high or debt payoff deserves its own lane. It was practically designed for real life in high-cost areas, where the 50% needs cap of 50/30/20 can feel like fiction.
Choose 70/20/10 if any of these sound like you:
- You live in a high-cost city where needs alone take up 55-65% of your income.
- You carry credit card or loan debt and want a dedicated 10% slice attacking it monthly.
- You find the needs-versus-wants distinction exhausting and want one simple number to watch.
The 70/20/10 method also shines if you want to build an emergency fund faster. You can temporarily redirect the 10% toward your emergency fund until it hits your target, then switch it back to debt or giving.
Can You Combine Both Budget Methods Into a Hybrid?
Yes, you can combine the 50/30/20 and 70/20/10 budget rules into a hybrid that fits your situation. Here are two popular hybrids that real people actually use:
The 50/25/15/10 split. Keep the 50% needs cap and 25% wants from 50/30/20, borrow the 10% debt-or-giving slice from 70/20/10, and keep 15% for savings. Good for mid-debt-payoff budgets that still want a clear wants limit.
The income-stage method. Start with 70/20/10 while paying off debt or building your first emergency fund, because the structure is simpler. Once debt is gone and savings are on autopilot, graduate to 50/30/20 for finer control over lifestyle spending.
The golden rule for any hybrid: keep savings at 20% or higher.
How to Switch Budget Methods Without Messing Up Your Finances
The best moment to switch is at the start of a new month, so you get a clean slate instead of mixing two systems mid-cycle. Follow these steps for a smooth transition:
- Calculate your new buckets. Multiply your monthly take-home pay by each percentage. On $4,500 income, 70/20/10 gives you $3,150 for expenses, $900 for savings, and $450 for debt or giving.
- Automate the 20% first. Set up automatic transfers on payday. Money you never see is money you never miss.
- Give it three months before judging. Three months of data will tell you whether the new percentages fit your real life or need tweaking.
If you are switching because debt is your priority, read our guide on paying off debt faster to aim the 10% debt slice at the right balance first.
Frequently Asked Questions
Which is better: 50/30/20 or 70/20/10?
Neither is universally better. Choose 50/30/20 if you need a clear line between needs and wants and struggle with lifestyle creep. Choose 70/20/10 if your living costs are high, you carry debt, or you want a dedicated bucket for debt payoff or giving. Both save 20% of your income, so pick the one you will actually stick with.
Can I follow the 50/30/20 budget if my rent is too high?
Yes, with a temporary adjustment. If rent and fixed costs exceed 50% of your income, shift to something like 60/25/15 or 70/20/10 until your income rises or housing costs fall.
What should the 10% in the 70/20/10 rule be used for?
Use it for extra debt payments if you owe money, especially high-interest credit cards. If you are debt-free, direct it toward giving, a savings goal, or extra investing.
Do these budget rules work on a low income?
Yes, with adjusted percentages. On a tight budget, essentials can exceed 70% of income. Save whatever you can (even 5% is a win), cut the biggest expenses first, and grow your income.
Should savings come before debt payoff in these rules?
Build a small emergency fund of $1,000 first, then attack high-interest debt aggressively. In the 70/20/10 rule, that is exactly what the structure encourages: 20% savings for your safety net and investments, 10% aimed at debt.
How do I track a percentage budget without a spreadsheet?
Use your bank’s built-in spending categories, a simple notes app, or a free budgeting app that auto-categorizes transactions. For 70/20/10 you only need to watch one number: total spending versus the 70% cap. Ten minutes a week is plenty.
The Bottom Line
The 50/30/20 vs 70/20/10 budget debate has no universal winner, because both rules save exactly the same 20% of your income. What matters is which structure keeps you consistent. If you need bright lines between needs and wants, 50/30/20 is your rule. If you want one simple spending number plus a lane for debt or giving, 70/20/10 is your rule.
Pick one this week. Calculate your buckets from your real take-home pay, automate your 20% savings on payday, and give the method three honest months.
Ready to put your new budget into action? Pick your method today, then keep it on track with a weekly money review of just 10 minutes. For a deeper dive, read our 50/30/20 budget rule beginner’s guide.